
Serving all 50 States | 20+ Years Manufacturing Expertise | Certified Specialists
Footwear Manufacturing Insurance
Manufacturing Insurance Group provides specialized insurance coverage for footwear manufacturers, backed by 20+ years of industry experience structuring product liability coverage around manufacturing, design, and failure-to-warn exposure specific to footwear.
Trusted Carrier Partners
National Producer Number (NPN): 7642818
The Single Most Common Gap in Footwear Manufacturing Coverage
General liability does not cover a finished shoe once it ships and reaches a wearer. Product liability is the separate coverage that addresses manufacturing defects, design defects, and failure-to-warn claims, the three real legal categories a footwear injury claim can fall under. Footwear manufacturers need both lines working together, not one standing in for the other.
Coverage Built for Footwear, Not General Leather Goods
Manufacturing Insurance Group insures footwear manufacturers (NAICS 316210), a real, distinct category within leather and allied product manufacturing that carries its own production risks and its own liability profile. U.S. footwear manufacturing is a specialized, close-knit industry, roughly 214 companies employing about 10,000 workers nationwide, and coverage built for general leather goods will not always fit it well.
The biggest distinction most footwear manufacturers need to understand is the real difference between general liability and product liability. General liability covers injuries and property damage tied to your operations, a visitor hurt at your facility, a delivery accident. It does not cover a shoe that fails after it leaves your facility and causes an injury. That is a separate risk, covered by product liability, and it matters more in footwear than in many other product categories given how directly footwear performance connects to physical safety.
Whether you manufacture your own designs, produce for private-label brands, or work as a contract manufacturer, we build coverage around your real production model.
If footwear is one part of a broader leather goods operation, see our leather and allied product manufacturing insurance page for coverage across your full product line.
Our Coverages
Footwear Manufacturing Insurance Coverage Options
General Liability Insurance
A buyer visits your facility and is injured. A delivery driver is hurt loading finished product. General liability protects your footwear manufacturing business from third-party bodily injury and property damage claims tied to your premises and operations, separate from anything a finished shoe itself might cause.
Commercial Property Insurance
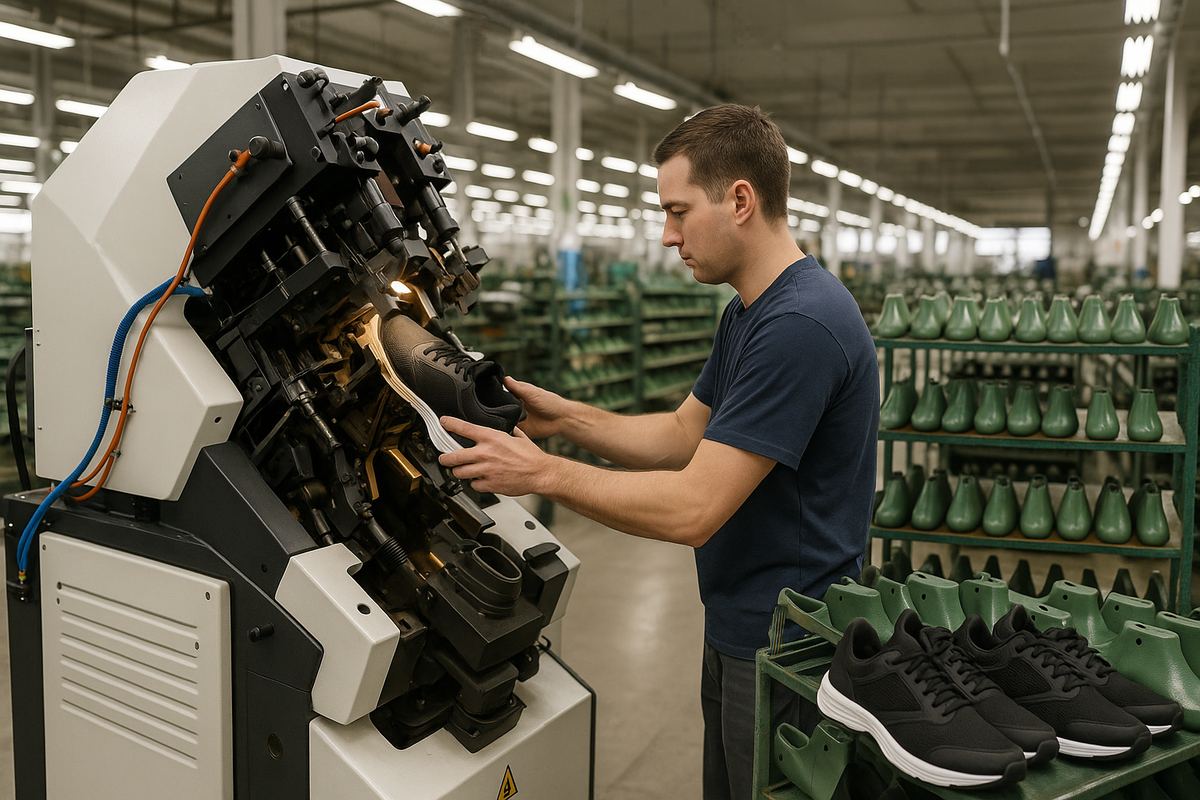
Cutting equipment, stitching lines, and molding machinery represent real capital investment, and finished footwear inventory carries real value sitting in your warehouse. Commercial property insurance protects your facility, equipment, and inventory against fire, storms, theft, and other covered losses.
Product Liability Insurance
This is the coverage that matters most in footwear manufacturing. A sole separates and causes a fall. Structural support fails and causes an injury. Product liability covers manufacturing defects, design defects, and failure-to-warn claims, the three real legal categories a footwear product liability claim can fall under, once a shoe leaves your facility and reaches a wearer.
Business Interruption Insurance
A fire or major equipment failure can shut down footwear production for months given how specialized cutting and molding equipment can be to replace. Business interruption insurance replaces lost income and covers ongoing expenses while you rebuild.
Workers Compensation Insurance
Cutting, stitching, and molding operations all carry real injury risk, from repetitive-motion strain to equipment-related accidents. Workers compensation is required in nearly every state and covers medical costs and lost wages when an employee is hurt on the production floor.
Supply Chain Insurance
Leather, synthetic materials, soling compounds, and hardware components often come from a concentrated supplier base. Supply chain insurance covers financial losses when a vendor failure or material shortage disrupts your production through no fault of your own.
Errors and Omissions Insurance
Private-label and contract manufacturing arrangements carry real professional exposure if a specification is missed or a sizing standard is not met. E&O insurance covers claims arising from those professional mistakes, separate from a product defect claim.
Equipment Breakdown Insurance
Cutting equipment, sole-molding presses, and stitching machinery are expensive and specialized. Equipment breakdown insurance covers the internal mechanical and electrical failures a standard property policy excludes, paying for repairs and the income you lose while equipment is down.
Directors and Officers Insurance
A serious injury claim or a private-label contract dispute can quickly become a leadership-level issue for a footwear manufacturer. D&O insurance protects your executives and board from personal liability tied to management decisions.
Employment Practices Liability
Wrongful termination claims, discrimination allegations, and wage disputes carry the same real cost for a footwear manufacturer as any other business. EPLI covers the legal defense and settlement costs tied to employment-related claims from your team.
A Real, Documented Workplace Safety Consideration
Adhesive and solvent exposure is a real, documented workplace safety consideration in footwear manufacturing. OSHA’s own Technical Manual identifies solvent vapor exposure as a cause of eye, respiratory, and skin irritation on production floors, and a peer-reviewed occupational health study of shoemakers specifically documented benzene-based solvent exposure in cementing and adhesive construction work, benzene being a recognized Group 1 carcinogen. This is a real factor in structuring workers compensation and workplace safety coverage for a footwear manufacturer, not a generic assumption.
Manufacturing Insurance Group has placed coverage for manufacturers across dozens of specialized industries for more than 20 years, including the broader leather and allied product manufacturers we also work with. If footwear is one part of a larger leather goods operation, we build one coordinated program around your full production mix.
Getting a Quote for Footwear Manufacturing Insurance
Ready to protect your operations? Get expert guidance and a custom quote today.
Frequently Asked Questions About Footwear Manufacturing Insurance
What is the difference between general liability and product liability for a footwear manufacturer?
General liability covers injuries and property damage tied to your business operations and premises, a visitor hurt at your facility, a delivery accident. It does not cover a shoe that fails after it ships and causes an injury to a wearer. That is a separate exposure covered by product liability, and it matters more in footwear than in many product categories given the direct connection between footwear performance and physical safety.
What kinds of product liability claims can a footwear manufacturer face?
Footwear liability claims generally fall into three real legal categories: manufacturing defects (a flaw introduced during production), design defects (a flaw in the shoe’s design itself, even when made correctly), and marketing or failure-to-warn defects (inadequate instructions or warnings). Product liability coverage should address all three.
Does product liability insurance cover the cost of a product recall?
Generally, no. Standard product liability insurance typically excludes the cost of repairing or replacing a defective product and does not automatically cover recall expenses. Footwear manufacturers who want recall protection specifically should discuss that as a separate coverage consideration.
Is workers compensation required for footwear manufacturers?
In nearly every state, workers compensation is required once you have employees. Cutting, stitching, and molding operations on a footwear production line all carry real injury risk, and workers compensation covers medical costs and lost wages when someone gets hurt.
Who can be held liable if a private-label or contract-manufactured shoe causes an injury?
Liability in a distribution chain can extend to the manufacturer, component makers, and distributors, not just the brand whose name is on the product. This is a real consideration for footwear manufacturers doing private-label or contract work, since your business can carry liability exposure even when another company’s brand is on the finished shoe.
How much does footwear manufacturing insurance cost?
Cost depends on your revenue, production volume, claims history, and coverage limits. Small to mid-size manufacturers broadly run between $3,000 and $25,000 a year for core coverage, roughly 0.5 to 1.5 percent of revenue, though a custom quote is the only accurate way to know your real cost.