
Serving all 50 States | 20+ Years Manufacturing Expertise | Certified Specialists
Sporting Goods Manufacturing Insurance
Manufacturing Insurance Group provides specialized insurance coverage for sporting goods manufacturers, backed by 20+ years of industry experience navigating the injury-liability severity and ASTM and CPSC compliance exposure unique to athletic equipment.
Trusted Carrier Partners
National Producer Number (NPN): 7642818
The Classification Risk Most Sporting Goods Manufacturers Miss
Whether your equipment is classified as sporting goods or gets swept into a toys and games classification can change both your premium and your regulatory exposure, and most manufacturers have no visibility into how that call gets made. Getting classification right at the start matters as much as the coverage itself.
Coverage Built for Athletic Equipment Risk, Not Generic Product Liability
Manufacturing Insurance Group insures sporting and athletic goods manufacturers (NAICS 339920), from protective equipment and training gear to team sports equipment and recreational products. This is one of the more liability-sensitive corners of manufacturing, and generic coverage rarely fits it well.
Sporting goods carry a real classification challenge that catches manufacturers off guard. A product built for professional or adult athletes can get swept into a “toys and games” classification meant for children’s products, changing your premium and your regulatory exposure with it. We have seen manufacturers blindsided by a reclassification they had no visibility into and no say over. Getting your classification right from the start matters as much as the coverage itself.
Add in real compliance exposure to ASTM International safety standards and Consumer Product Safety Commission oversight, plus the genuine injury-liability weight this industry carries, and it becomes clear why sporting goods manufacturers need a specialist, not a generalist.
See our full list of manufacturing industries we serve if sporting goods is not your only product line.
Our Coverages
Sporting Goods Manufacturing Insurance Coverage Options
General Liability Insurance
A visitor is injured touring your production floor. A delivery driver is hurt loading finished equipment. General liability protects your sporting goods manufacturing business from third-party bodily injury and property damage claims tied to your premises and operations, separate from any claim involving the equipment itself once it reaches an athlete.
Commercial Property Insurance
Molding equipment, cutting and stitching machinery, and finished inventory represent real capital tied up in your facility. Commercial property insurance protects your buildings, equipment, and inventory against fire, storms, theft, and other covered losses.
Product Liability Insurance
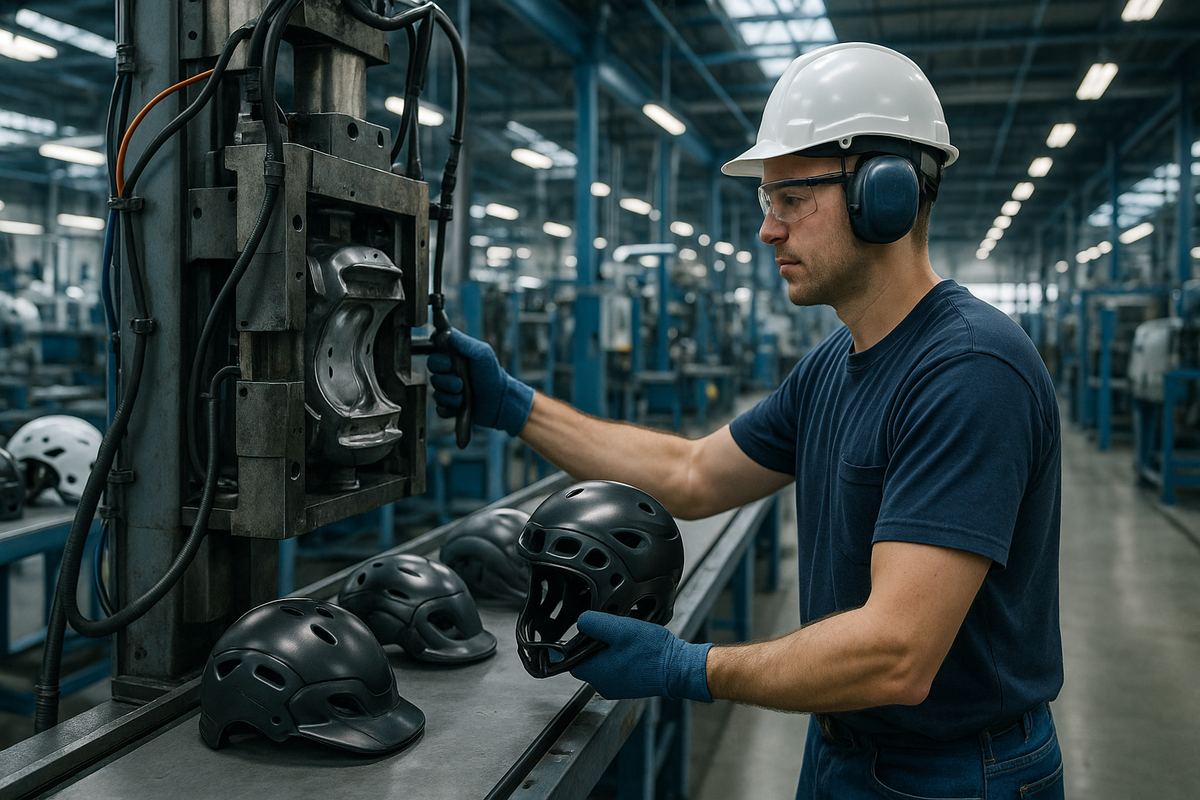
This is the coverage that matters most in this industry. A helmet fails on impact. A piece of protective gear does not perform as designed. Product liability provides critical protection against injury claims tied to equipment failure, the single largest liability exposure sporting goods manufacturers face, and the exposure serious enough that helmet manufacturers have historically needed dedicated industry liability pools to manage it.
Business Interruption Insurance
Sporting goods manufacturing often runs on seasonal production cycles tied to sports calendars. A fire or equipment failure that halts production during a peak season can cost far more than the same event during a slow month. Business interruption insurance replaces lost income and covers ongoing expenses while you rebuild.
Workers Compensation Insurance
Molding, cutting, stitching, and assembly equipment all carry real injury risk on a sporting goods production line. Workers compensation is required in nearly every state and covers medical costs and lost wages when an employee is hurt on the job.
Supply Chain Insurance
Specialty foams, composite materials, and technical fabrics used in protective equipment often come from a limited supplier base. Supply chain insurance covers financial losses when a vendor failure or material shortage disrupts your production through no fault of your own.
Errors and Omissions Insurance
Manufacturers who design equipment to custom specifications, for a school district, a league, or a private-label retail partner, carry real professional liability exposure if a specification is missed or a design choice causes a customer financial harm. E&O insurance covers claims arising from those professional mistakes.
Equipment Breakdown Insurance
Injection molding presses, compression molding equipment, and automated stitching lines are expensive and specialized. Equipment breakdown insurance covers the internal mechanical and electrical failures a standard property policy excludes, paying for repairs and the income you lose while equipment sits idle.
Directors and Officers Insurance
A product recall or a serious injury claim can quickly become a leadership-level crisis in sporting goods manufacturing. D&O insurance protects your executives and board from personal liability tied to management decisions during exactly that kind of event.
Employment Practices Liability
Wrongful termination claims, discrimination allegations, and wage disputes carry the same real cost for a sporting goods manufacturer as any other business. EPLI covers the legal defense and settlement costs tied to employment-related claims from your team.
Getting Classification and Coverage Right From the Start
Carriers typically weigh intended user age, marketing channel, and safety certification on file when classifying athletic equipment, factors a manufacturer rarely sees spelled out before a quote comes back. Equipment marketed to adult or professional athletes with ASTM certification documented has real support for a sporting goods classification instead of a toys and games default.
Injury-liability severity is the other major factor. Real safety standards from ASTM International and real oversight from the Consumer Product Safety Commission exist precisely because equipment failure in this industry can cause serious injury, not property damage alone. That is why product liability carries more weight here than in most manufacturing categories, and why the industry has historically needed dedicated liability pools for high-risk categories like football helmets.
Manufacturing Insurance Group has placed coverage for manufacturers across dozens of specialized industries for more than 20 years. We build your policy around your real production and injury-liability profile, not a generic template.
Getting a Quote for Sporting Goods Manufacturing Insurance
Ready to protect your operations? Get expert guidance and a custom quote today.
Frequently Asked Questions About Sporting Goods Manufacturing Insurance
Why does my sporting goods classification matter for insurance?
Whether your equipment is classified as sporting goods or gets swept into a toys and games classification can meaningfully change both your premium and your regulatory exposure. Manufacturers often have little visibility into how a carrier arrives at that classification, which is why getting it right at the start, with an agent who understands the distinction, matters.
What safety standards apply to sporting goods manufacturers?
ASTM International maintains real, industry-recognized safety standards covering athletic and fitness equipment reliability, and the Consumer Product Safety Commission provides federal oversight of consumer sporting goods. Compliance with these standards is a real factor carriers consider when underwriting product liability coverage.
Why is product liability so important for sporting goods manufacturers?
Equipment failure in this industry can cause serious physical injury, not just property damage, which makes injury-liability severity higher than in many other manufacturing categories. Protective equipment like helmets carries some of the highest liability exposure in all of manufacturing, historically serious enough that the industry has needed dedicated liability insurance pools for certain product categories.
Is workers compensation required for sporting goods manufacturers?
In nearly every state, workers compensation is required once you have employees. Molding, cutting, stitching, and assembly equipment on a sporting goods production line all carry real injury risk, and workers compensation covers medical costs and lost wages when someone gets hurt.
How does seasonality affect sporting goods manufacturing insurance?
Sporting goods production often follows seasonal cycles tied to sports calendars, which means a covered loss that halts production during a peak season can cost significantly more than the same event during a slow period. Business interruption coverage should reflect your real seasonal revenue pattern, not a flat annual average.